Possible: Fast Cash & Credit

Screenshots
Details
- Rating
- 28.00K reviews
- Version
- 2.3.7
- Developer
- Possible Finance - A Public Benefit Corporation
Analysis by Norviv
When an unexpected expense lands between paydays, I want a clear way to judge whether borrowing is actually useful—or likely to make next week harder. Possible: Fast Cash & Credit is a finance app from Possible Finance - A Public Benefit Corporation, built around access to cash and credit-building. I see its strongest use as a short-term bridge for someone with a specific, manageable need, not as a routine way to stretch an income that is already committed.
What the app is for—and what that means in practice
Possible’s pitch is appealing because it brings borrowing and a chance to build credit into one mobile experience. The app is free to download, has an Everyone age rating, and is available for Android and iOS. It has an average rating of 4.4 from around 59,000 ratings, with more than a million installs. Those figures suggest broad interest, but they do not tell me whether a particular borrower will qualify or whether an advance will fit their budget.
The key question I would ask before applying is not simply, “Can I get money quickly?” It is, “Can I repay on the schedule without missing rent, utilities, groceries, or another bill?” A cash advance can solve a timing problem, but it does not create extra income. I would open the app with the amount and purpose already in mind, then compare the repayment dates with my actual paydays and bills before accepting any offer.
Where it fits among borrowing options
Compared with a conventional personal loan, an app-based advance can feel more direct and suited to a smaller, immediate shortfall. A bank or credit-union loan may be a better fit when I need a larger amount, want a longer repayment period, or can qualify for a lower-cost option. The trade-off is that traditional applications can involve more steps and may be less convenient when the need is urgent.
Compared with a credit card, Possible may appeal to someone who wants a defined repayment plan rather than adding to a revolving balance. But a card with a low rate, an existing promotional offer, or a bill-payment arrangement could be cheaper. I would also consider asking a utility provider or landlord about a payment extension before borrowing. Those alternatives can take a phone call, but they may avoid taking on a new repayment commitment altogether.
For someone comparing cash-advance apps, the details that matter are the actual offer, timing, repayment dates, and total amount due—not just the speed implied by a quick-cash message. I would read each screen carefully and avoid treating an eligibility check as a guarantee of approval. The right choice depends on the terms shown to the individual and whether the repayment fits their circumstances.
A realistic way to use it
Imagine a car repair bill arriving a few days before payday, while rent and food money are already set aside. I would first ask the repair shop whether it offers a payment arrangement, then check whether another lower-cost source is available. If neither works and I consider Possible, I would request only what the repair requires rather than borrowing extra “just in case.” Before confirming, I would write down the repayment date and amount alongside the bills due around that time.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That small bit of planning matters because an advance can shift pressure rather than remove it. If repayment comes out when several other expenses are due, the original emergency may be followed by another shortfall. A useful personal rule is to test the repayment against a conservative version of the next pay period: assume no unexpected extra income and include ordinary necessities. If the plan only works when everything goes perfectly, I would look for another option.
Questions worth answering before you borrow
Will everyone who downloads the app receive an advance? No—access depends on the app’s assessment and the offer presented to the individual. The published description of Possible does not make a download equivalent to approval, so I would avoid relying on the money until an offer is actually available. I would also check the amount and repayment details shown in the app rather than assuming another person’s experience will match mine.
Is this a good way to build credit? It can be relevant to someone who wants credit-building as part of the product, but I would treat that as a possible longer-term benefit, not a reason to borrow money I do not need. Payment reporting does not erase the obligation to repay, and the effect of any credit activity depends on the person’s wider credit file. If my main goal is building credit, I would compare this borrowing-based route with other options that may suit my situation better.
How quickly will the money arrive? The original experience described a deposit usually arriving within a day after approval, but I would not plan a time-critical payment around an assumed arrival. Processing can depend on circumstances, so I would confirm the timing in the app and keep a backup plan for an urgent bill. If a missed deadline would trigger a serious consequence, contacting the biller directly may be the safer first step.
What should I check before accepting? I would read the full repayment schedule, the amount due, any applicable costs, and the consequences of a payment being difficult to make. I would also confirm that the linked bank account and payday information are accurate. A few minutes reviewing those details is more useful than focusing only on how quickly the application moves.
Getting Started with Possible
First things first, downloading and setting up Possible: Fast Cash & Credit is a breeze. Available on both Android and iOS, I was pleasantly surprised at how user-friendly the interface is. The app guides you through the entire process, so even if you’re not tech-savvy, you’ll find it easy to navigate.
Once you’ve signed up, the app conducts a quick eligibility check. No need to worry about your credit score here—they focus more on your income and banking activity. This means you can get access to funds even if your credit history isn’t perfect.
How It Works
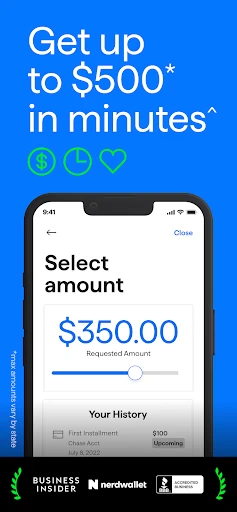
So, how exactly does it work? The process is quite straightforward. After you’re approved, you can request a cash advance directly through the app. The funds are then deposited into your bank account, usually within a day. Talk about fast!
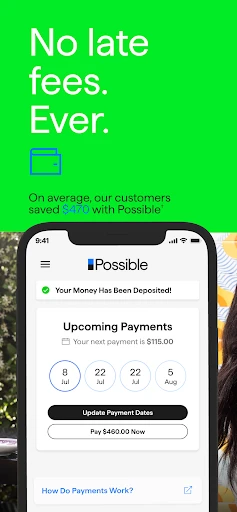
Repayment is equally simple. The app sets up a repayment schedule based on your paydays, making it easier to manage. Plus, you can pay back early without any penalties. This flexibility is a huge plus for anyone juggling multiple financial responsibilities.
Building Credit with Possible
One of the unique features of this app is its focus on credit building. Unlike traditional payday loans that can negatively affect your credit score, Possible reports your payment activity to major credit bureaus. This means if you’re consistent with your payments, you could see a positive impact on your credit score over time.
And let’s be honest, having a decent credit score opens up a lot of doors. Whether it’s renting an apartment or getting a car loan, building your credit is a smart move for the future.
My Experience
Personally, I found the app to be a reliable solution during a financial hiccup. The transparency of the terms and the no-hidden-fee policy were reassuring. Plus, the customer support team was super responsive, which is always a big plus in my book.
However, it’s essential to remember that while this app can provide quick cash, it’s not a substitute for proper financial planning. The interest rates are higher than traditional loans, so it’s best used for emergencies rather than regular expenses.
The app’s current version is 2.3.7, following its release on January 25, 2018. That gives the product a longer history than a brand-new lending app, while the version number alone does not establish which features changed or how the experience has evolved. For an existing user, I would focus on what the current screens and terms say today rather than assuming an older walkthrough still matches every step.
That distinction is especially useful when updating an app or returning after a while. Check the current repayment details and any notices before making a new request; do not rely on memory of a previous offer. The core appeal remains straightforward, but the specifics that affect a borrowing decision are personal and should be reviewed each time.
There are also practical limits to the app’s convenience. An easy interface cannot make an unsuitable repayment schedule affordable, and the credit-building angle should not be mistaken for a guaranteed score increase. I would not use an advance to cover a recurring monthly gap, finance discretionary purchases, or replace a budget conversation with myself about expenses that keep exceeding income.
Possible is most compelling for someone facing a one-off, time-sensitive expense who has a dependable upcoming payday and can identify exactly how repayment will fit. It is less suitable for someone whose income is unpredictable, who is already behind on several obligations, or who needs borrowing over a longer period. In those situations, talking with creditors, seeking lower-cost local support, or comparing a credit-union option may be more helpful than adding another payment.
One useful habit is to keep a simple record after any advance: the reason for borrowing, the due dates, and whether the next pay period felt tighter. That makes it easier to tell whether the app solved an isolated timing mismatch or became a pattern. If the same shortfall returns every month, I would treat that as a signal to look for a structural fix rather than repeat short-term borrowing.
Overall, Possible: Fast Cash & Credit delivers on its promise of fast cash and credit building. If you’re in a bind and need a quick financial fix, it’s definitely worth considering. Just remember to use it wisely!
Frequently Asked Questions
01What is Possible: Fast Cash & Credit, and how does it work?
Possible: Fast Cash & Credit is a mobile app designed to provide users with quick access to small loans and help build credit. It offers short-term loans without requiring a high credit score, making it accessible to more people. Users can apply directly through the app, receive funds quickly, and repay over time while potentially improving their credit score.
02Is Possible: Fast Cash & Credit safe to use?
Yes, Possible: Fast Cash & Credit is safe to use. The app employs encryption to protect user data and financial information. Additionally, it complies with state and federal regulations to ensure users' rights are protected. However, users should always practice caution by using secure passwords and monitoring their accounts regularly.
03What are the eligibility requirements for getting a loan with Possible?
To be eligible for a loan with Possible, users must be at least 18 years old, have a valid bank account, and provide proof of consistent income. A regular paycheck is necessary since it determines the repayment schedule. Unlike traditional lenders, Possible does not require a high credit score, making it more accessible to users with varying credit histories.
04How does Possible: Fast Cash & Credit impact my credit score?
Possible reports loan repayments to major credit bureaus, which can positively impact your credit score if payments are made on time. Consistent, timely repayments demonstrate financial responsibility and can help improve your credit over time. However, late payments or defaults may negatively affect your credit score, so it's crucial to manage repayments carefully.
05What fees and interest rates are associated with Possible's loans?
Possible charges fees and interest rates that vary depending on the loan amount and repayment terms. These fees are clearly outlined in the app before you accept the loan, ensuring transparency. While the rates may be higher than traditional loans due to the convenience and speed offered, they're competitive within the short-term lending market.


